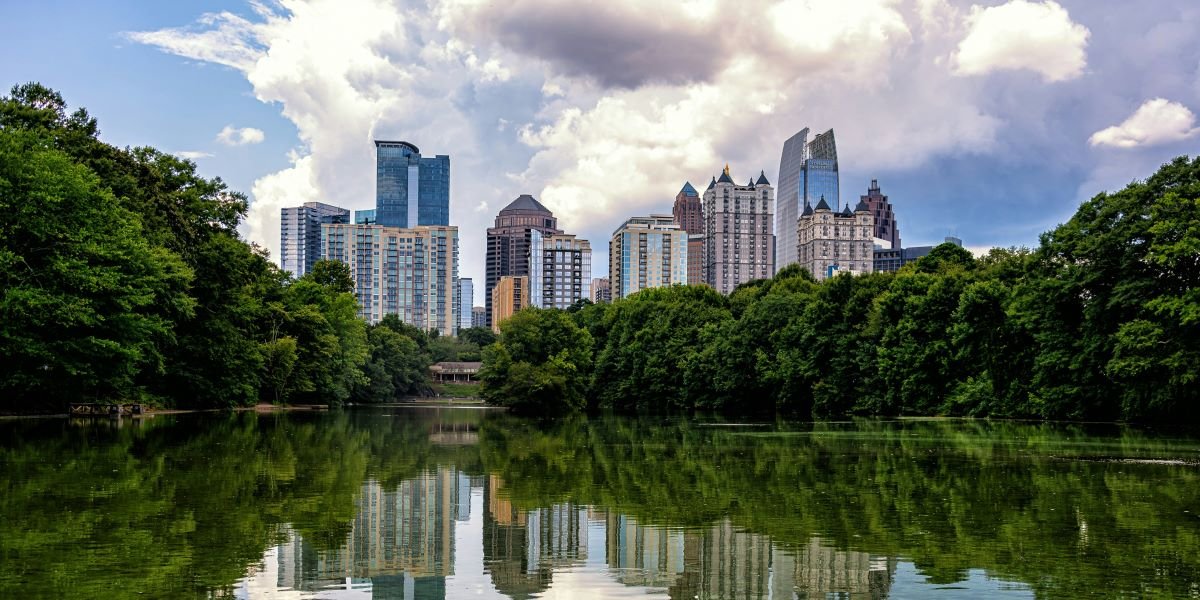
Downtown Atlanta Tops 34,000 Residents as 2026 State of Downtown Report Shows Visitors Returning

Downtown Atlanta is home to more than 34,000 residents, and visits have recovered to 85 percent of pre-pandemic levels, according to the 2026 State of Downtown report Downtown Atlanta Inc. released October 28. The findings arrived on the city’s second annual Downtown Day, alongside new renderings of The Stitch, the planned park over the Downtown Connector.

Key Takeaways

  • Visits to downtown Atlanta have returned to 85 percent of pre-pandemic levels.
  • Developers have added 201 multifamily housing units downtown since January 2026.
  • About 1 in 3 downtown residents is under 25.
  • Retail occupancy in South Downtown has reached 90 percent as new shops and restaurants open.
  • The Stitch has $50 million secured for phase one and is applying for a $60 million federal resilience grant.
  • Kyle Waide, president and CEO of the Atlanta Community Food Bank, takes over Downtown Atlanta Inc. on December 1.

State Of Downtown Report Shows A Growing Residential Base

Downtown Atlanta Inc., the umbrella organization for the former Central Atlanta Progress and the Atlanta Downtown Improvement District, presented the 2026 State of Downtown report at a breakfast on October 28. The numbers point to a neighborhood shifting from a weekday office district into a place where people live.

More than 34,000 people now call downtown home, and the population skews young, with about 1 in 3 residents under 25. That reflects downtown’s mix of college campuses, transit lines, and entertainment venues. Since January, 201 new multifamily units have opened. Shirlynn Fortson, vice president of planning and economic development at Downtown Atlanta Inc., said residents matter because they “create consistent demand for restaurants, retailers, services, and public spaces.” Unlike convention crowds or game-day traffic, residents spend money downtown every day of the week.

Retail is following that demand. In South Downtown, new shops and restaurants have pushed retail occupancy to 90 percent. Visits across downtown have climbed back to 85 percent of pre-pandemic levels. The report credits investment in The Stitch, the renovation of the former CNN Center, and campus upgrades at Georgia State University.

Office Vacancies Remain A Downtown Challenge

The report does not hide the difficult numbers. Downtown still carries millions of square feet of vacant office space, a holdover from the shift to remote and hybrid work. Mayor Andre Dickens told the breakfast audience, “We can’t build downtown’s future around the market 20 years ago,” and pointed to housing as central to the next phase.

For property owners and small businesses, that shift matters. Empty office floors mean fewer weekday lunch customers, while new residents bring evening and weekend traffic. Downtown’s recovery now depends on how quickly housing and mixed-use projects can make up for the office demand that has not come back.

The Stitch Moves Toward Phase One Construction In 2027

The Stitch remains downtown’s long-range project. Atlanta Downtown Stitch Inc., the nonprofit formed to build and run the project, plans a park of about 17 acres over a three-quarter-mile stretch of the Downtown Connector. The park would reconnect Downtown and Midtown across I-75/85, and the full project is estimated at more than $700 million.

Phase one begins with street and infrastructure work in 2027, and the park cap will follow. Jack Cebe, president and CEO of Atlanta Downtown Stitch Inc., said the project has secured $50 million for phase one from sources including the City of Atlanta and the Atlanta Regional Commission. The Stitch lost more than $150 million in previously awarded federal funding in 2025. It is now applying for a $60 million federal grant for infrastructure resilience, since the park is designed to capture more than 3 million gallons of rainwater a year that could otherwise flood the Downtown Connector.

The latest public designs show an indoor-outdoor Gateway Pavilion along Peachtree Street, cafe space, and green space. New renderings were on display again during Downtown Day.

Downtown Day Puts The Neighborhood On Display

Downtown Atlanta Inc. and the City of Atlanta presented the second annual Downtown Day on the same day as the report. The program included a lunchtime party on the Broad Street Boardwalk, games at Centennial Yards, and a salute to the Downtown Ambassadors who keep streets clean and safe. After the inaugural event in 2025 and a summer of World Cup crowds, organizers say Downtown Day will now return every year.

Kyle Waide Takes The Helm At Downtown Atlanta Inc. In December

The report also marks a leadership change. Kyle Waide, who has led the Atlanta Community Food Bank since 2015, becomes president and CEO of Downtown Atlanta Inc. on December 1. He succeeds A.J. Robinson, who led the organization for nearly 23 years. Waide inherits a downtown with a growing residential base, an office market still searching for demand, and a park project that needs more funding to move forward.

FAQs

How Many People Live In Downtown Atlanta?

More than 34,000 people live in downtown Atlanta, according to the 2026 State of Downtown report. About 1 in 3 residents is under 25.

What Is The Stitch In Atlanta?

The Stitch is a planned park and neighborhood built over the Downtown Connector (I-75/85) to reconnect Downtown and Midtown. It is led by the nonprofit Atlanta Downtown Stitch Inc.

When Will Construction On The Stitch Begin?

Phase one starts with street and infrastructure work in 2027. The park cap over the highway will follow those improvements.

Who Is The New Leader Of Downtown Atlanta Inc.?

Kyle Waide, president and CEO of the Atlanta Community Food Bank, becomes president and CEO of Downtown Atlanta Inc. on December 1, succeeding A.J. Robinson.

A Practical Guide to Commercial Real Estate Financing for Small Businesses

For many business owners, rent is the largest fixed expense on the books. Every month, it leaves the business and builds equity for someone else. At some point, a question naturally arises: should we buy our own building?

Owning the property where you operate can stabilize costs, build long-term wealth, and give you control over your space. It also ties up capital, adds responsibilities, and involves financing that works differently from most business loans. This guide covers what owner-occupied commercial real estate financing looks like, how to evaluate whether buying makes sense, and how to approach lenders wisely.

Field note: Lenders distinguish between owner-occupied properties, where your business uses most of the space, and investment properties, where tenants generate the income. Owner-occupied loans are typically evaluated based on your business’s cash flow, while investment loans focus on rental income. This guide focuses on owner-occupied purchases.

Why Business Owners Buy

Predictable occupancy costs. A fixed-rate mortgage locks in a payment that will not rise with market rents.

Equity and wealth building. As the loan is paid down and the property potentially appreciates, the owner builds an asset that can be sold, refinanced, or passed on.

Control. No landlord can decline to renew your lease, raise rent sharply, or restrict improvements you want to make.

Potential rental income. If the building has extra space, leasing it to other businesses can offset your mortgage.

Tax considerations. Owners may be able to deduct mortgage interest and depreciation, subject to tax rules and professional advice.

Why Some Owners Wait

Capital requirements. Down payments for commercial property commonly range from 10 to 30 percent, and closing costs, inspections, and improvements add more.

Reduced flexibility. If your business outgrows the space or needs to relocate, selling a building takes time.

Maintenance and risk. Roofs, HVAC systems, parking lots, and property taxes become your responsibility.

Opportunity cost. Money spent on a down payment could instead fund equipment, hiring, or marketing that grows the business faster.

Field note: A useful exercise is to compare the total monthly cost of owning, including mortgage, taxes, insurance, and a maintenance reserve, with your current rent plus expected increases over the next decade. Include the value of equity you would build. The answer is rarely obvious, which is why the exercise matters.

The Main Financing Options

SBA 504 Loans

The 504 program is designed specifically for major fixed assets such as real estate. A typical structure includes a bank loan covering about half the project, a loan from a certified development company backed by the SBA covering a large portion of the remainder, and a borrower contribution often around 10 percent. Long, fixed-rate terms on the CDC portion make payments predictable. Owner-occupancy requirements apply.

SBA 7(a) Loans

The 7(a) program can also finance real estate, sometimes alongside working capital or equipment in the same loan. It offers flexibility for mixed-purpose projects.

Conventional Commercial Mortgages

Banks and credit unions offer commercial mortgages with terms that vary widely. Many feature shorter amortization periods or balloon payments, meaning the loan must be refinanced or paid off after a set number of years. Down payments are often higher than SBA options.

Seller Financing

Occasionally, a property owner will finance part of the purchase, especially in slower markets or for unique properties.

Field note: Pay close attention to the difference between the loan’s term and its amortization. A loan amortized over 25 years with a 10-year term will have payments calculated as if you had 25 years, but the remaining balance comes due in full after 10. Plan for that balloon from day one.

A Simple Own-Versus-Rent Illustration

Suppose a dental practice pays $6,500 per month in rent, with increases of about 3 percent per year. A comparable building nearby is available for $1,100,000.

With 10 percent down, or $110,000, the practice would finance roughly $990,000. Depending on the rate and structure, the mortgage payment might land somewhere between $6,500 and $7,500 per month. Add property taxes, insurance, and a maintenance reserve, and the total monthly cost of ownership could reach $8,500 or more.

At first glance, owning looks more expensive. But each payment reduces the loan balance, and over ten years the practice might build several hundred thousand dollars in equity, plus any appreciation. Meanwhile, rent would have climbed to nearly $8,500 per month by year ten with nothing to show for it. The right answer depends on the numbers, the practice’s long-term plans, and what else the down payment could have accomplished. These figures are illustrative only.

What Lenders Evaluate

Commercial real estate lenders examine both the property and the business occupying it.

Debt service coverage. Lenders want your business’s cash flow to cover the new mortgage payment with room to spare. Many look for a coverage ratio of 1.25 or higher.

Loan-to-value. The loan amount compared with the appraised value determines how much equity you need to contribute.

Credit and experience. Personal and business credit histories, as well as your track record running the business, matter.

Property condition. Appraisals, inspections, and environmental reports help lenders confirm the property’s value and identify risks.

Business stability. Several years of tax returns and financial statements demonstrate whether the business can carry the obligation.

Occupancy plans. For owner-occupied programs, lenders will confirm that your business will use the required share of the building. If you plan to lease part of it to tenants, be clear about how much and on what terms, since that can affect which loan programs are available.

Costs Beyond the Down Payment

Owners are often surprised by how many expenses accompany a commercial purchase:

  • Appraisal and environmental assessment
  • Property inspection and survey
  • Legal and title fees
  • Loan origination and guarantee fees
  • Insurance, including property and liability coverage
  • Property taxes, often due shortly after purchase
  • Renovations or tenant improvements
  • Moving and setup costs

Build all of these into your budget, and keep reserves for unexpected repairs after closing.

Researching Lenders the Right Way

Commercial real estate financing varies significantly among lenders. Some banks specialize in owner-occupied properties in certain industries. Some excel at SBA 504 projects. Others prefer conventional loans for well-established borrowers. Rates, terms, prepayment penalties, and balloon structures differ, sometimes dramatically.

Before applying, take time to understand the market. Comparison platforms such as Business Loans Engine and Business Loans Companies list lenders across several business financing products, which can help narrow the options that fit your situation. Review sites such as Best Rated Business Loans and Merchant Guidance offer additional background on how borrowers describe their funding experiences.

Field note: Ask every prospective lender about prepayment terms. Some commercial loans include step-down penalties or yield maintenance clauses that make early refinancing expensive. Others allow prepayment freely. This can matter a great deal if rates fall or your plans change.

Apply With Your Best Match

Once you have narrowed the field, choose the one lender that best fits your property type, down payment, timeline, and business profile, and apply there.

Commercial real estate applications involve appraisals, environmental reviews, and extensive underwriting. Submitting your package to several lenders at the same time can lead to multiple hard credit pulls, which may lower your score just as underwriters are evaluating it. Lenders may also be less willing to invest resources in a file they believe is being shopped widely. Meanwhile, purchase contracts carry deadlines, and coordinating several lenders’ requests for documents and inspections can create confusion that jeopardizes your closing.

Working with a single lender keeps the process organized and gives that lender every reason to move your file forward. If they decline, ask for specific reasons, address them, and move to your next choice.

A Pre-Purchase Checklist

  • Confirm that the property suits your business for at least the next five to ten years
  • Compare total ownership costs with leasing over the same period
  • Verify zoning allows your intended use
  • Obtain inspections and review environmental reports
  • Calculate whether business cash flow covers the payment with a comfortable margin
  • Keep a cash reserve for repairs and operating needs after closing
  • Review loan terms, amortization, balloon dates, and prepayment provisions
  • Consult an attorney and accountant before signing

Is Buying Your Building the Right Move?

Buying your building can be one of the most significant financial decisions a business owner makes, turning a monthly expense into a long-term asset. It is not right for every business or every stage, and the outcome depends on the property, the financing terms, and the company’s plans. Do the math honestly, understand the financing structures, research lenders carefully, and apply with the one that fits.

Disclaimer: This article is intended for general informational and educational purposes only and should not be considered financial, legal, or professional advice. The information provided may not apply to every individual or business situation. Readers are encouraged to conduct their own research and consult qualified professionals before making any financial or business decisions.

First Marriage vs. Second Marriage Divorce Rates: What the Data Shows

When a person gets married for the second time, they may believe that they have learned from the mistakes of their first marriage. They may be older and more financially stable, and they may feel that they have a better understanding of what they want in a partner. Even so, research shows that remarriages often face challenges that first marriages do not. In many cases, when a second marriage ends, the divorce process can be more complicated than a first-time divorce.

In the United States, second marriages are generally more likely to end in divorce than first marriages. A second divorce may involve unique legal issues, especially when it takes place later in life. Because of this, legal representation from an experienced divorce attorney can be crucial to make sure a person approaches the end of their second marriage the right way.

How Do Divorce Rates Compare for First and Second Marriages?

Determining the statistics related to divorce in the United States is not always easy, because the specific numbers are not tracked by the government, and different studies approach divorce in different ways. However, based on data provided by the National Center for Health Statistics, it is estimated that around 40 to 50% of first marriages end in divorce. According to the Institute for Family Studies, around 60 to 70% of second marriages end in divorce. Third marriages may have divorce rates as high as 73%.

This trend is part of an increase in what is often called “gray divorce,” meaning divorce among people age 50 and older. According to Pew Research Center, the divorce rate for this age group is around 10.3 divorces per 1,000 married women. A study by Bowling Green State University also found that around 40% of people who get divorced are over the age of 50, and older people who have remarried are at a higher risk of divorce.

Why Are Second Marriages More Likely to End in Divorce?

There are several factors that may contribute to the higher rates of divorce after remarriages, including:

Blended Family Challenges

Many people who remarry have children from previous relationships. Blending two families can create tension over parenting styles and discipline. Children may not have good relationships with a new stepparent, and parents may find it difficult to determine whether to prioritize a new spouse or their kids. Research has found that second marriages involving stepchildren face greater risks of divorce than couples who do not have children.

Financial Pressure From a Prior Divorce

When they get married for the second time, a person may still be paying child support or alimony from their first divorce. Alimony, which may also be called spousal support or maintenance, is money that one former spouse pays to the other after a divorce. These payments can reduce the money available to the new household, which can lead to arguments or financial struggles that may increase the likelihood of divorce.

Less Fear of Divorce

Someone who has already been through a divorce knows they can survive one. That experience may make them more willing to leave an unhappy marriage instead of trying to work through marital problems and repair a relationship.

Moving Too Quickly

Some people remarry soon after getting divorced without fully processing what went wrong. They may bring unresolved issues from their first marriage into the second one, which can lead to conflict or cause either spouse to realize that they should not have gotten married.

What Issues May Need to Be Addressed in a Second Divorce?

A second divorce often involves more complex issues than a first divorce. Each spouse may have brought property, debts, and family obligations into the marriage. They may need to address concerns related to:

Prenuptial Agreements

People who are entering a second marriage may be more likely to ask for a prenuptial agreement, which is a contract couples sign before marrying that explains how property and financial support will be handled if they get a divorce. If a prenuptial agreement exists, it may control many of the decisions in the divorce.

Separate Property vs. Marital Property

Property a person owned before getting married is considered separate property, while property acquired during a couple’s marriage is marital property that may be divided in a divorce. In a second marriage, one or both spouses may have more separate property than they did in a first marriage. Problems may arise when separate property gets mixed with marital property. For example, if a person used money from their first divorce settlement to help buy a home with their second spouse, it may be difficult to sort out who owns what.

Children and Stepchildren

In a second marriage, child custody and child support issues may involve children from the current marriage, a previous marriage, or both. While a stepparent generally does not have a legal duty to support a stepchild after a divorce, and stepparents usually do not have automatic rights to custody or visitation, some states may allow stepparents to request visitation in certain situations. If a stepparent adopts a stepchild, they will have a right to share child custody, and they may have child support obligations.

What Issues Matter Most in a Divorce Later in Life?

When people divorce in their 50s, 60s, or later, they often have less time to rebuild their finances before retirement. Some of the most important issues that they may need to address during the divorce process include:

  • Dividing retirement accounts and pensions, which often requires a special court order called a qualified domestic relations order (QDRO) that tells a retirement plan how to split the funds
  • Deciding who will keep the family home and whether either spouse can afford it on a single income
  • Determining whether spousal support will be paid, which may depend on the length of the marriage, each spouse’s age and health, and their ability to work
  • Understanding Social Security benefits, since a person who was married for at least 10 years may be able to collect benefits based on their ex-spouse’s work record
  • Planning for health insurance, especially for a spouse who is not yet eligible for Medicare
  • Updating wills, trusts, powers of attorney, and beneficiary designations on life insurance and retirement accounts

How Can an Attorney Help With a Second Divorce or Gray Divorce?

Ending a second marriage or getting a divorce later in life can raise questions about property, retirement, and financial support. A skilled divorce attorney can review a prenuptial agreement to determine whether it is valid, help trace separate property that may have been mixed with marital assets, explain how to address retirement accounts, and determine whether either spouse may be eligible for spousal support. By receiving legal representation during the divorce process, a person can end their marriage successfully while protecting their interests and preparing for the future.

Disclaimer: This article is for general informational and educational purposes only and does not constitute legal advice. Divorce laws, property division rules, and spousal support requirements vary by state and individual circumstances. The divorce statistics cited are estimates based on available research and may differ depending on the source, methodology, and time period studied. Readers should consult a qualified family law attorney in their jurisdiction for legal guidance specific to their situation.